Policy reminders
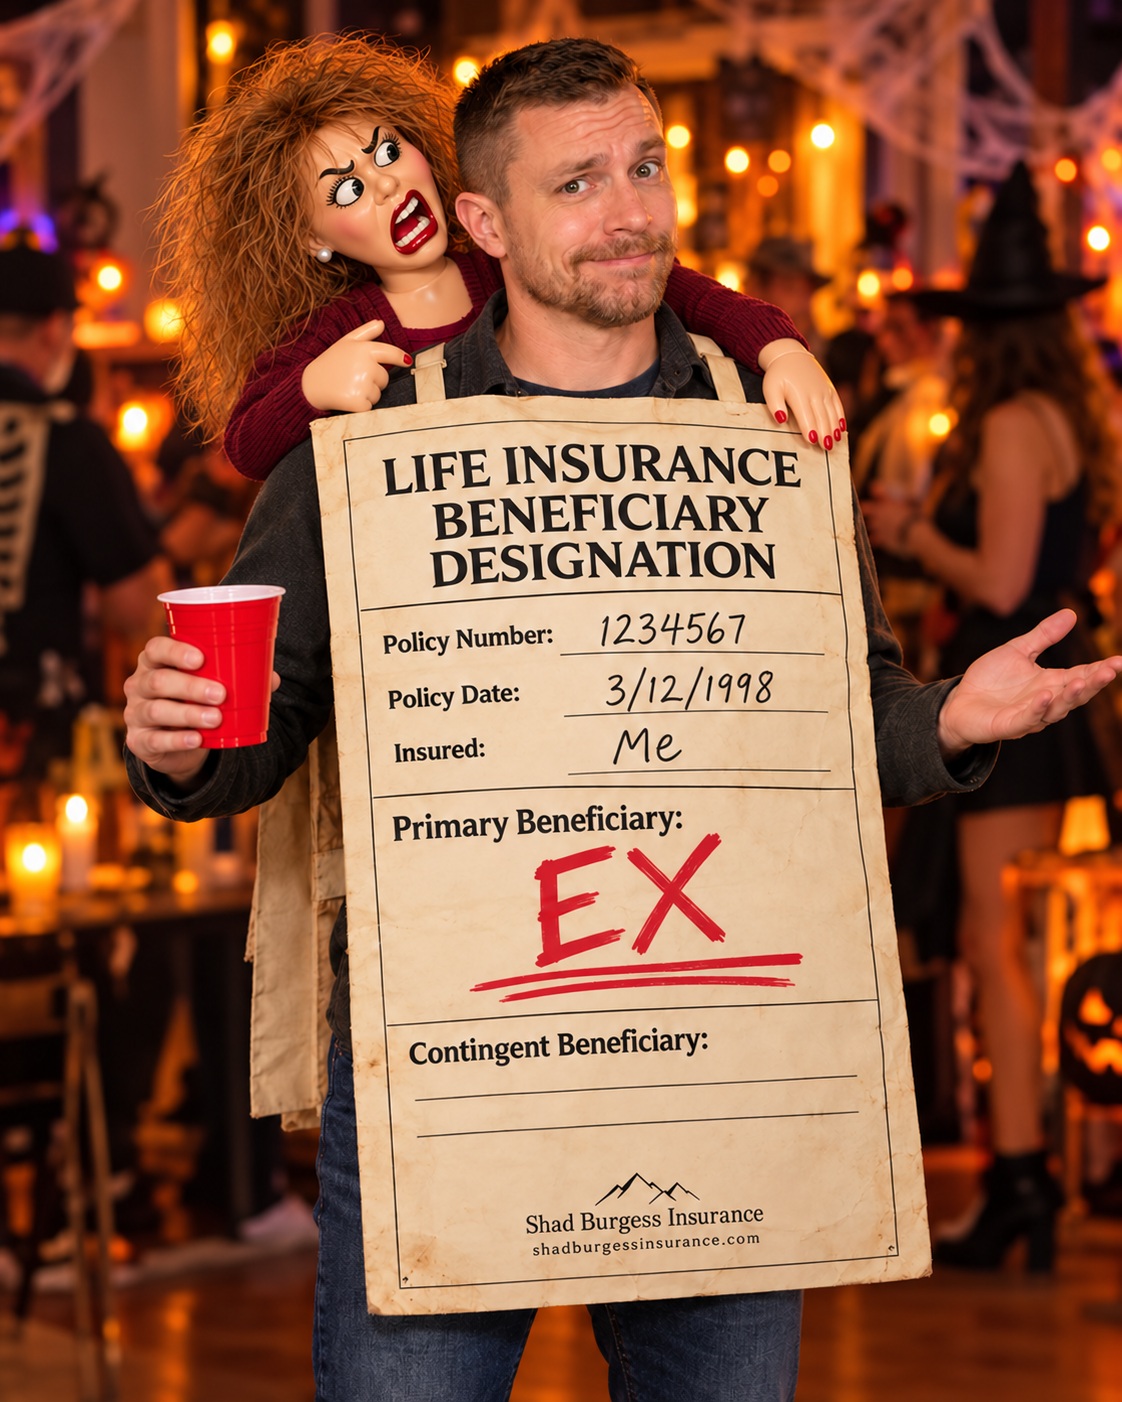
The scariest name on an old life insurance policy? An ex.
A little Halloween humor and a simple reminder: life changes. Check whether the names on an old life insurance policy still reflect today’s wishes.
Read the guide ↗ Shad Burgess InsuranceOHIO & PENNSYLVANIA
Beneficiaries & family protection
You can name a child as a life insurance beneficiary, but insurers generally do not pay benefits directly to minors. Learn the practical options for Ohio and Pennsylvania families.
Use the free family protection checklist →
Yes, a minor child can be named in a life insurance beneficiary plan, but insurers generally do not pay a death benefit directly to a minor. If the policyholder dies while the child is still underage and no valid arrangement is in place, payment may be delayed while a court appoints someone to manage the money.
The practical goal is to name both the child you want to protect and the legal structure or responsible adult who can receive and manage the benefit for that child.
A beneficiary designation tells the insurer who should receive the death benefit. A minor generally cannot sign a settlement agreement or control a large financial account, so the insurer usually needs an authorized adult, custodian, guardian, or trustee before releasing the money.
That can mean extra paperwork, legal expense, and delay at the exact time the family needs the benefit. Planning the designation while the policyowner is alive can make the intended path clearer.
Ohio and Pennsylvania each have a version of the Uniform Transfers to Minors Act. These laws allow property to be held by an adult or qualified institution as custodian for a minor when the designation is created correctly.
Ohio law provides beneficiary wording that names an adult or trust company as custodian for the child under the Ohio Transfers to Minors Act. Pennsylvania law similarly allows a person to nominate a custodian in a beneficiary designation under the Pennsylvania Uniform Transfers to Minors Act.
The exact wording matters. Ask the insurer whether its beneficiary form accepts a custodial designation and have an Ohio or Pennsylvania attorney review the arrangement when legal advice is needed.
A properly created trust can receive the benefit and direct how a trustee manages it for the child. The trust can address who manages the money, what expenses it may support, and when the child may receive funds.
A trust involves legal drafting and administration. An insurance agent can explain the beneficiary form, but an attorney should create or review the trust and coordinate its exact legal name with the policy designation.
Some parents consider naming a relative and simply asking that person to use the money for the child. If the adult is named personally rather than in a legally defined role, the death benefit generally belongs to that adult after payment.
A verbal promise is not the same as a custodial or trust arrangement. The adult could die, face creditors, experience a divorce, or use the money differently than intended. Get legal advice before relying on this approach.
Hypothetical example: a Pennsylvania parent wants a life insurance benefit to support a 7-year-old child. Instead of listing only the child’s name, the parent speaks with the insurer and an attorney, then completes a beneficiary designation naming a trusted adult as custodian for the child under Pennsylvania law.
If the insured dies while the child is still a minor, the custodian can seek payment in that legal capacity and manage the funds under the applicable rules. This example is educational, not a guarantee that a particular form or designation will be accepted.
A primary beneficiary is first in line to receive the benefit. A contingent beneficiary generally receives it if no primary beneficiary can receive it. Naming several people also requires clear percentages that total 100%.
Review the designation after a birth, adoption, marriage, divorce, death, custody change, or move between states. Policy records—not a casual note or conversation—control what the insurer sees when a claim is filed.
Who should benefit from the policy? Will any beneficiary still be a minor if a claim occurs? Who should manage the money? Does the insurer accept a state-law custodial designation? Would a trust better fit the family’s needs? Who should serve as a backup?
Confirm full legal names, contact information, relationships, percentages, and the exact wording required by the insurer. Keep the current policy and beneficiary confirmation where a trusted adult can find them.
Start by deciding what you want the benefit to accomplish for the child—housing, daily support, education, final expenses, or another family need. Then choose coverage and a beneficiary arrangement that work together.
Shad Burgess Insurance helps Ohio and Pennsylvania families compare available life insurance options and complete the insurer’s beneficiary information in plain English. Use the website’s booking button or request form to begin a no-pressure conversation.
Shad Burgess Insurance does not provide legal or tax advice. Trusts, guardianships, custodial arrangements, and beneficiary rights depend on the facts, state law, insurer requirements, and completed legal documents.
Can I list my child by name? Yes, but listing a minor alone may lead to delay because the insurer generally will not pay the child directly.
Does naming a guardian in my will automatically control the life insurance benefit? Not necessarily. The policy’s beneficiary designation and any valid trust or custodial wording matter. Coordinate the documents with an attorney.
Can I name more than one child? Yes. State the percentage for each beneficiary and plan for how each minor’s share would be managed.
Should I name my estate instead? That choice can involve probate, creditor, timing, and tax considerations. Discuss it with an attorney before changing the designation.
Can I change beneficiaries later? Many policyowners can change revocable beneficiaries, but ownership rights, irrevocable designations, court orders, and policy terms can limit changes. Ask the insurer before acting.
NAIC — Life Insurance Buyer’s Guide: choosing a beneficiary and minors (accessed November 5, 2026) ↗
Ohio Department of Insurance — Life and Annuity Insurance Guide (accessed November 5, 2026) ↗
Pennsylvania Insurance Department — Life Insurance consumer guidance (accessed November 5, 2026) ↗
Related guide — Would Your Family Know Where to Find Your Life Insurance? ↗
Sources checked for this article on 2026-11-05.
Ohio and Pennsylvania readers considering permanent coverage: compare whole life insurance options with Shad.
Policy reminders
A little Halloween humor and a simple reminder: life changes. Check whether the names on an old life insurance policy still reflect today’s wishes.
Read the guide ↗
Family protection
A short beneficiary checklist to help your family locate your policy and know whom to contact.
Read the guide ↗